Owning a home in Cyprus: easier to borrow, harder to afford

How the dream of owning a home in Cyprus has changed from crisis to stability — and why the struggle continues

2012: The Year of Risk

When Cyprus's banking system collapsed, mortgages exceeded 5.50% and a generation was locked out.

2017–2021: The Era of Low interest rates

ECB quantitative easing pushed mortgage rates below 2.50%. Borrowing felt almost costless for the first time.

2022: Inflation Returns

Energy crisis and soaring prices forced the ECB into the sharpest rate hikes in history. Households felt the squeeze.

What Changed

At the peak of the 2012 banking crisis, a typical €200,000 mortgage over 25 years at 5.50% cost €1,228 every month. By the end of the term, borrowers had repaid €368,400 — including €168,400 in interest alone. The weight of that debt shut an entire generation out of the property market.

Today, at the current average rate of 3.24%, the same loan costs €974 a month and €292,200 in total. That is €254 less every month and €76,200 saved in interest over the life of the loan.

Monthly Instalment Over Time
How much a €200,000 mortgage cost borrowers each month from the 2012 crisis to today
201220152017201920212022202320242026

Three Chapters

2012–2015: The Cost of Risk

With Cyprus's banking system in turmoil, borrowing was a luxury few could afford. Rates on new mortgages exceeded 5.00%, shutting a whole generation out of the property market.

For small and medium-sized businesses, borrowing costs reached 6.00%. Banks weighed down by non-performing loans effectively stopped lending, stifling any attempt at growth.
2016–2021: Near-Zero Rates

The ECB responded to the crisis with quantitative easing, and for five years the market became used to borrowing at almost no cost. Between 2017 and 2021, the average mortgage rate in Cyprus fell to historic lows of 2.00% to 2.50%.

Demand for new loans surged. The average rate on large business loans of more than €1 million fell to close to 3.00%, allowing companies to restructure debt and restart major developments.

2022–2024: Inflation Returns

Cheap money came to an end in 2022, when the energy crisis and inflation forced the ECB into the most aggressive rate rises in its history. Within 18 months, mortgage rates climbed back above 4.50% to 5.00%.

Thousands of borrowers on variable rates saw their monthly instalments rise by hundreds of euros, putting households under strain. Financing costs for small and medium-sized businesses jumped to 5.50% to 6.00%, again freezing investment plans.

Cyprus Is No Longer the Weak Link

In 2012, Cyprus borrowed at a large risk premium compared with the rest of Europe. The island was at the epicenter of the eurozone banking crisis, and lenders demanded compensation for uncertainty. Today, the average mortgage rate in Cyprus sits at 3.24%, below the European average of 3.54%. Cypriot banks now hold excess liquidity, which allows them to absorb shocks without immediately passing every ECB rate rise on to customers.

Borrowers Changed Their Habits

The volatility of 2022 taught households a hard lesson: variable rates that once seemed clever became traps when inflation surged. Monthly instalments for thousands of families rose by hundreds of euros within months, straining budgets and forcing difficult choices. That experience reshaped behaviour. The vast majority of new mortgages in Cyprus are now taken out at a rate fixed for the first three to five years, protecting households from inflation and further rate rises. The market learned to value certainty over marginal savings, and that shift has made the system more resilient.

The October Decision

The European Central Bank's Governing Council meets on October 28 and 29 to set interest rates. Some policymakers are open to a 25-basis-point rise, from 2.50% to 2.75%, because of inflationary pressure from energy prices. Most analysts and markets, however, expect the ECB to wait until its December meeting, when it will have more economic data.

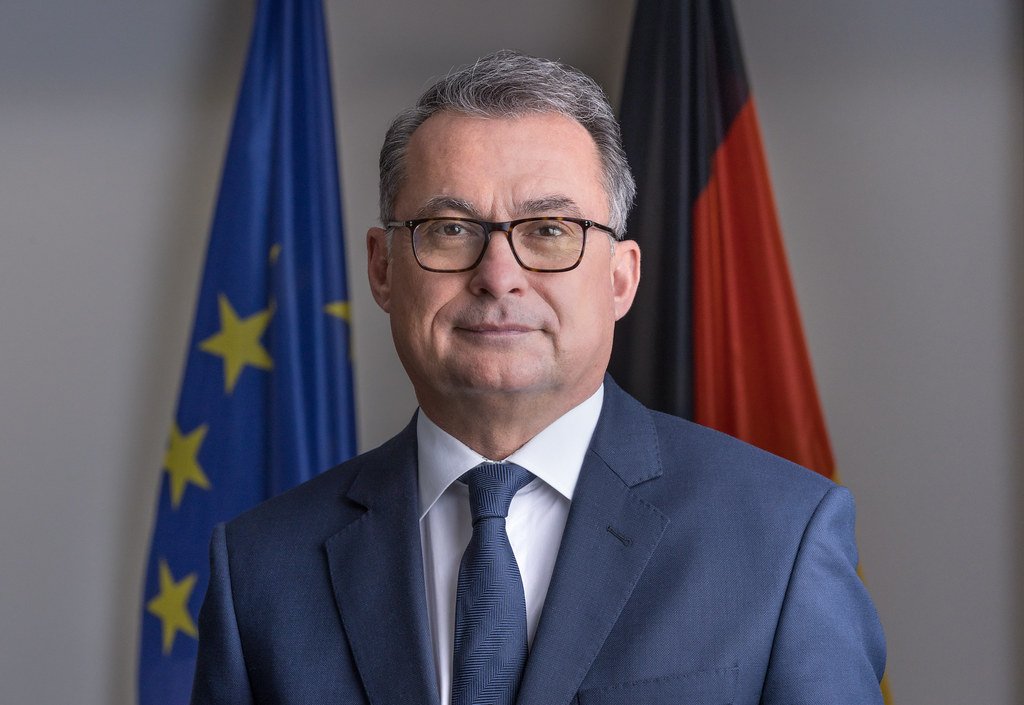
The division reflects a fundamental tension: hawkish members like German central bank governor Joachim Nagel insist the fight against inflation should not be abandoned halfway. Latvian governor Martins Kazaks noted that inflation is almost double the ECB's 2% target and that further tightening may be needed.

But others, including French governor Emmanuel Moulin, suggest that markets could do part of the ECB's work by pushing up borrowing rates themselves, reducing the need for formal policy moves.

Market participants considered it likely that the ECB would not want to use up all its ammunition now, particularly as it had been the first central bank to start raising rates this cycle. It would instead give itself time to measure the effects of its policy before deciding its next step.

Voices from the Governing Council

What ECB policymakers are saying ahead of the October meeting

What It Means for You

If You're on a Variable Rate

Borrowers who took out loans or remained on variable rates at the peak of the inflation crisis in 2023 saw their instalment rise to €1,146 euros a month, at a rate of 4.80%. The fall in the average mortgage rate to 3.24% leaves them €172 a month better off today. But another 25-basis-point rise would reverse some of that relief, adding roughly €30 to monthly payments.

If You're Looking to Buy

For young couples trying to buy a home, the main obstacle has shifted from the cost of borrowing to soaring prices for property and building materials. Mortgage rates may be more historically reasonable, but the upfront capital required — the deposit, legal fees, and purchase price itself — has become the true barrier. Lower interest no longer compensates for the fact that homes cost more than ever.

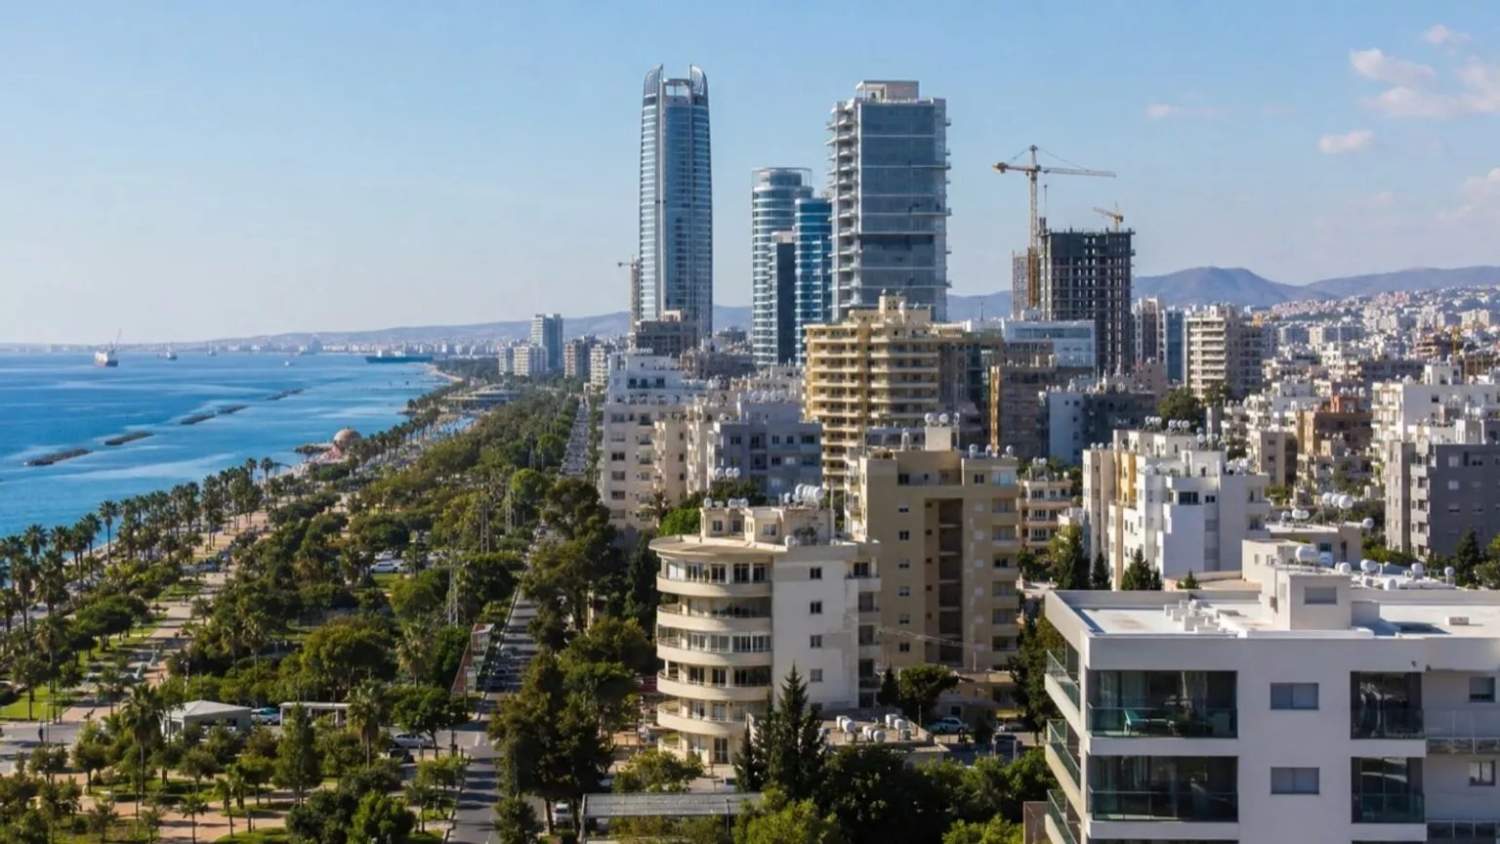
For sale sign in front of a modern Cypriot apartment building

Common Questions

What borrowers in Cyprus are asking about rates, risk, and the road ahead

Why are Cyprus mortgage rates now below the European average?
In 2012, Cyprus borrowed at a large risk premium because its banking system was in turmoil. Today, Cypriot banks hold excess liquidity and the local system has stabilised, allowing them to offer rates below the European average of 3.54%. The country is no longer the weak link it once was.
What happens if the ECB raises rates again?
A 25-basis-point rise would push the policy rate from 2.50% to 2.75%, and banks would likely pass some of that increase on to borrowers. On a €200,000 mortgage, expect monthly instalments to rise by roughly €30. Borrowers on fixed rates for the next few years would be protected.
Should I choose a fixed or variable rate now?
The vast majority of new mortgages in Cyprus are now taken out at a rate fixed for the first three to five years. The lesson of 2022—when variable-rate borrowers saw instalments jump by hundreds of euros—was that certainty is worth more than marginal savings. Fixed rates can protect you from inflation and further ECB hikes.
Has the cost of borrowing really fallen, or is this temporary?
Compared with the 2012 crisis, borrowing costs have fallen dramatically and remain well below that peak. But the era of near-zero rates (2017–2021) is over. Today's 3.24% average is a middle ground—lower than crisis levels, higher than the free-money period. The ECB's next moves will determine whether rates stay here or edge up further.
Why is it still so hard to buy a home if rates are lower?
Lower interest rates reduce monthly instalments, but they do not reduce the upfront capital required. Property prices and building materials have soared, making the deposit, legal fees, and purchase price itself the main barrier for young buyers. The real obstacle has shifted from the cost of borrowing to the cost of buying.
Made with Scrollytelling